
The most mainstream technology is the one you never notice. By that standard, stablecoins — digital tokens designed to hold a steady one-to-one value with the dollar — are having their most mainstream year yet. They are turning up not in speculative trading apps, where they began, but in the plumbing of everyday commerce: checkout options, cross-border payroll, marketplace payouts and remittances, often converted to ordinary money before the recipient ever sees a token.
The logic is transactional rather than ideological. Moving dollars through conventional international channels is slow and fee-heavy, especially outside banking hours. A regulated stablecoin can settle in minutes, at any hour, for a fraction of the cost — which is why payment companies have spent the past two years integrating them behind interfaces customers already trust.
What Mainstream Actually Looks Like
It does not look like shoppers brandishing crypto wallets. It looks like an online store whose payment processor settles the day’s takings instantly instead of in three days; a freelancer abroad who receives dollars in an app and spends them locally; a remittance whose fees visibly shrink. Industry coverage by Reuters and others has chronicled card networks and processors building exactly this invisible layer.
For merchants, the attraction is cash flow and cost. Card acceptance fees are a permanent tax on small margins, and any rail that credibly undercuts them gets a hearing — provided customers do not have to change their behaviour to use it. That proviso is why the token usually stays backstage.
Why the Pace Is Deliberately Careful
Regulators are determined that this mainstreaming not outrun the rules. New frameworks in the United States and Europe require payment stablecoin issuers to be licensed, to hold reserves in cash and short-dated government securities, and to prove it with regular attestations. The Federal Reserve and fellow central banks continue to flag the risks: an issuer is a promise, and promises need supervision, redemption rights and honest accounting.
The caution has a history. The 2022 failure of an unbacked algorithmic token wiped out billions and taught a durable lesson — stability is a property of reserves and governance, not of branding. Fully reserved issuers now compete partly on the quality of their audits, a sentence that would have sounded absurd in crypto’s wilder years. More market coverage sits in our business section.
Who Benefits First
The earliest clear winners are people failed by the old rails: families receiving remittances, small exporters waiting weeks for payment, savers in high-inflation economies holding dollars because their own currency melts. For them, a dollar token is not an investment thesis; it is a better envelope for money they already earn and send.
Shoppers in stable-currency countries may notice the least change — which is precisely the point. Mainstream adoption, in payments, means the new rail wins on price and speed while asking nothing new of the user.
Steady Tokens, Steady Questions
Questions remain, and they are the right ones: how concentrated issuer power should be allowed to become, how financial-crime controls keep pace, and what happens if a major token ever faces a run. The careful pace of the current rollout reflects those unknowns.
But the direction is set. Dollar tokens have left the trading floor and entered the checkout line — quietly, regulated, and increasingly ordinary. In payments, ordinary is the highest compliment there is.
The Checkout Test
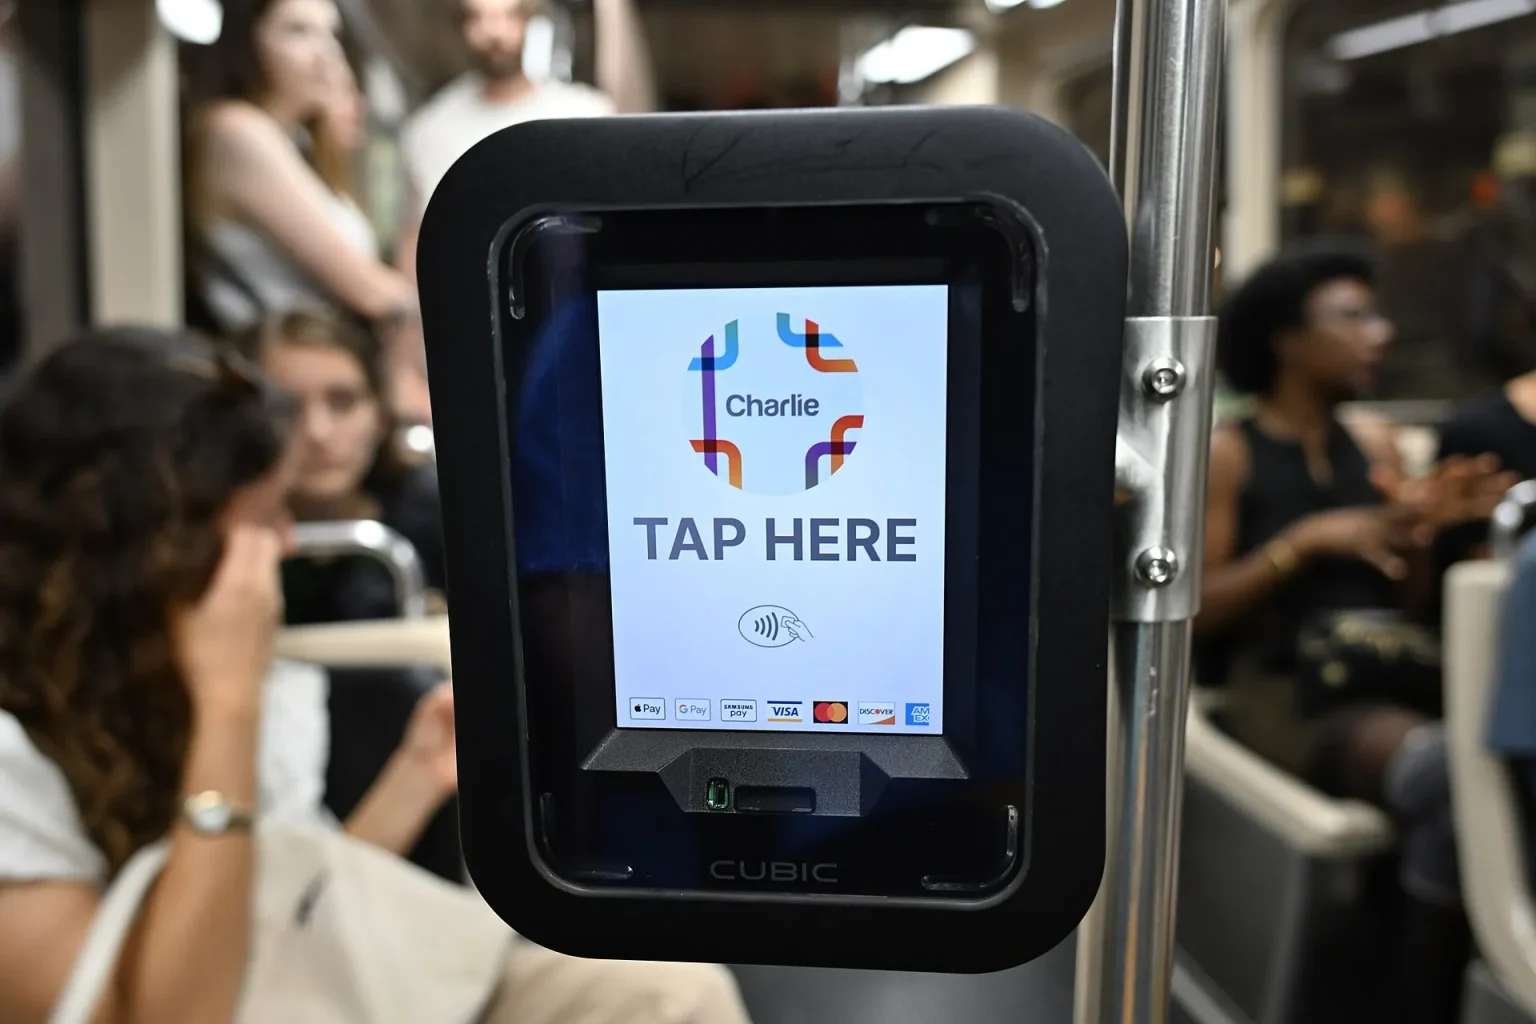
Ultimately, stablecoins at the checkout face the oldest test in payments: the queue. A payment method survives if it is faster, cheaper or more reliable than the card it replaces — for the shopper and the shop alike — without asking either to learn anything new. Tokens currently win that test behind the scenes, in settlement, more often than they win it in the customer’s hand.
That division of labour may be permanent, and there is no shame in it. Most people neither know nor care how card payments clear; they care that they do. If dollar tokens make the invisible part cheaper and quicker, mainstream will not announce them. It will simply include them.